

Direct Express® Mobile
by Fifth Third Bank
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
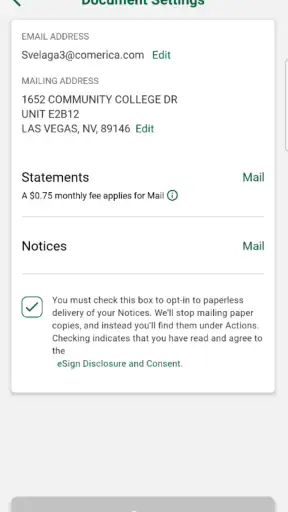
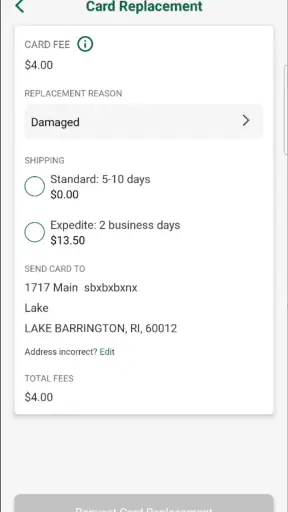
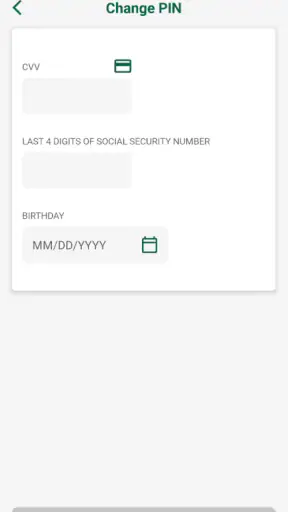
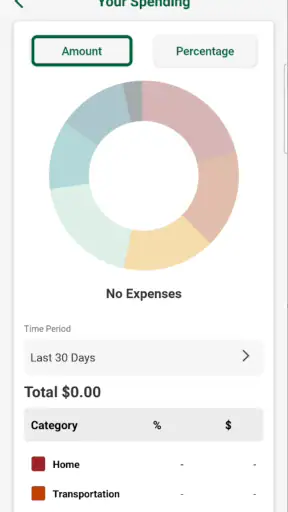
 Analysis by Getfullapps
Managing federal benefits can feel unnecessarily complicated when every purchase, balance check, or cash withdrawal depends on knowing exactly what is available. Direct Express® Mobile is built for a narrower purpose than a typical banking app: it supports people who receive federal benefits through a Direct Express prepaid debit card. I found that focus both useful and limiting. It keeps the experience centered on card access rather than trying to become a full financial hub, but it also means this is not the right replacement for every checking-account or budgeting app.
Developed by Fifth Third Bank, this free finance app gives eligible cardholders a mobile way to stay connected with their prepaid account. Its audience is clearly reflected in its Everyone content rating, while its broad adoption is shown by more than a million installs and an average rating of 4.6 from roughly 192 thousand ratings. Those numbers suggest that many users find the basic service dependable, although popularity alone does not remove the need to check whether it fits your particular card and benefit arrangement.
How Direct Express® Mobile fits into everyday money management
I find a shared-phone scenario useful for judging any finance app: convenience can help someone keep track of a Direct Express card, but account information still belongs to the cardholder. I’d begin by thinking about who can unlock the device and what might be visible at a glance; that practical boundary shapes how comfortably the app fits into a household routine.
A focused tool rather than a complete bank
My first impression is that the app makes the most sense when I treat it as a companion to the Direct Express card, not as a general-purpose banking platform. The central question is simple: can I quickly understand my available funds and manage card-related tasks without relying on a desktop browser or calling for every small update? That narrow purpose is a strength for someone who wants less clutter.
People who receive benefits on a prepaid card often need practical visibility more than investment charts, loan tools, or elaborate spending categories. A mobile account view can be especially helpful before buying groceries, paying a bill, or deciding whether there is enough money left for transportation. I would rather open a focused app for that than navigate through features I will never use.
At the same time, a prepaid debit card is not identical to a conventional checking account. That distinction matters. Users looking for overdraft tools, a broad bill-pay ecosystem, linked savings goals, or a complete household budget may find the experience too limited. The app serves the card relationship first; it does not turn that relationship into a full-service bank account.
Where it helps in a realistic day
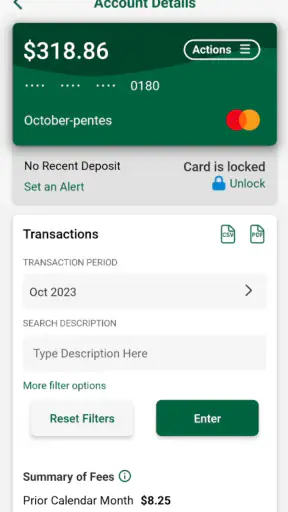
Imagine receiving a benefit deposit and planning several expenses across the week. Before leaving home, I can use the app to check the card position instead of guessing from an old receipt. At a store, that quick check can prevent an awkward declined transaction. Later, after a purchase, reviewing the account activity can help me recognize whether the remaining balance makes sense.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That workflow is more valuable than it sounds because prepaid spending has a hard limit. A traditional credit card may approve a purchase while creating a future payment obligation, but a prepaid card generally makes the available balance immediately relevant. The app therefore works best as a quick decision-making tool: check before spending, review after spending, and keep the card information close when traveling or handling recurring expenses.
I also see a benefit for caregivers or family members who help someone manage benefits, provided the account holder handles access appropriately and respects the service’s security requirements. A clear mobile view can make conversations about timing and available funds easier. It should not replace the cardholder’s control, but it can reduce the need to interpret paper records or remember every transaction.
What the current release tells me
The current version is 9.4, and the app was released on December 4, 2021. I read those details as evidence of an established product rather than a brand-new experiment. The important point is not simply the version label; it is that the app has had time to become a regular access point for people who depend on the Direct Express card.
That maturity raises expectations. An established finance app should feel predictable, protect sensitive information, and make routine tasks easy to repeat. I do not want a dramatic redesign every time I need to confirm a balance. For this kind of service, consistency is part of usability. A familiar path to the information I need is often more valuable than a visually ambitious interface.
However, a version number does not by itself prove that every part of the experience is equally polished. Updates can improve compatibility or correct problems without changing the way users interact with the account. I would judge the app by whether it remains dependable on my device, clearly communicates account information, and lets me recover from common mistakes without unnecessary friction.
The effect on existing cardholders
For an existing Direct Express user, the biggest change is usually behavioral rather than financial: account checking becomes something I can do during the day, not only when I have access to a computer or a statement. That can make spending decisions more deliberate. Instead of treating the card balance as a surprise, I can build a habit of checking it before important purchases.
There is also a useful separation between convenience and control. The app can make information easier to reach, but it does not remove the need to protect the physical card, keep login details private, and examine transactions carefully. A mobile shortcut is helpful only when the account holder remains alert. I would never treat an app notification or a remembered balance as a substitute for reviewing the actual account activity.
Users moving from occasional card use to frequent mobile checking may notice that the app changes how they plan. A person who receives a fixed benefit amount can divide the balance mentally across groceries, utilities, medicine, and transportation. Even without sophisticated budgeting features, regular visibility can support that simple method. The trade-off is that the user has to create the budgeting discipline; the app is not a complete financial coach.
Practical habits that make the app more useful
I recommend opening the app at three specific moments: after a benefit deposit, before a larger purchase, and after an unfamiliar transaction. This is more useful than checking constantly because each visit has a purpose. It also creates a simple record of what I expected to see and what actually happened.
Another good habit is to avoid making a purchase based only on an approximate balance remembered from yesterday. Pending activity, recent spending, or timing around deposits can affect what is available. When the purchase matters, I would check directly in the app and leave a small cushion rather than planning down to the last dollar.
A less obvious trade-off is convenience versus device dependence. Mobile access is excellent when the phone is charged, connected, and working normally. It is less reassuring if the phone is lost, replaced, or unavailable during an urgent purchase. I would keep the physical card accessible and know how I will handle account questions outside the app. The app should be an additional access route, not my only plan.
Security and access deserve attention
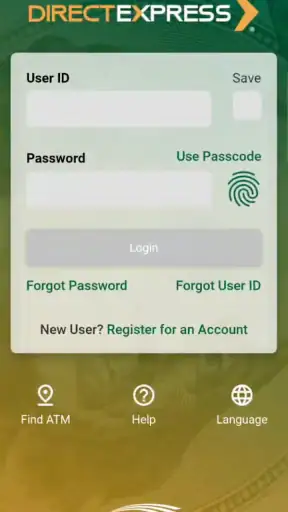
Finance apps require a different level of care from entertainment or shopping apps. I would use a screen lock on the phone, avoid sharing login credentials, and be cautious when signing in on a public or borrowed device. These steps are basic, but they matter more when the app is connected to benefit funds.
I would also pay attention to the exact account information shown after signing in. If something looks unfamiliar, the right response is to investigate through the official support route rather than repeatedly guessing at passwords or ignoring the issue. A mobile interface can make access feel casual, but the underlying account remains financially important.
People who share a phone should think carefully before enabling any convenience that exposes account details on the lock screen. A balance preview may save a tap, yet it can reveal private information to anyone who sees the device. In my view, discreet access is preferable to maximum convenience for a benefits account.
Where it falls short compared with alternatives
Compared with a conventional bank app, Direct Express® Mobile is more specialized. A bank application may offer checking and savings accounts, transfers between products, detailed budgeting, check deposits, and a wider set of financial services. Those tools are useful for users who want one place to manage several parts of their money.
Compared with a budgeting app, this service is also less analytical. A budgeting platform may categorize spending across multiple accounts and present longer-term trends. That can be better for someone trying to reduce expenses or plan a monthly target. Direct Express® Mobile is more appropriate when the immediate need is card access and awareness of available funds.
Compared with carrying out everything through customer service or a website, the mobile option should be more convenient for routine checks. Yet convenience does not automatically mean that every complicated issue belongs in the app. Questions about eligibility, disputed activity, account restrictions, or a lost card may require a more direct support process. I would not assume that a mobile screen can resolve every account problem.
The app is therefore a poor fit for someone who does not use a Direct Express prepaid card, wants a normal checking account, or expects advanced personal-finance planning. It may also disappoint users who need extensive customization. Its value comes from being relevant to a particular cardholder, not from offering the largest possible feature set.
Questions I would settle before relying on it
The first question is whether the app applies to my specific card arrangement. Since it is designed around Direct Express, I would confirm that my card is supported before building my daily routine around it. The store summary identifies the service as a prepaid debit card for federal benefit recipients, so eligibility is central rather than incidental.
The second question is whether my phone can run it. The minimum operating-system requirement is version 9, which covers many devices but still matters if I use an older phone. I would check the device before troubleshooting an installation problem. Keeping the operating system reasonably current is also sensible for a financial app, provided the phone supports the update.
The third question is whether mobile access replaces every other method of managing the card. I would answer no in practical terms. The app can be the fastest way to check information, but I would retain the physical card and know where to seek help if the phone, login, or account presents a problem.
The fourth question is whether it can replace a budgeting system. For me, it cannot. I can use the balance and transaction information as the foundation for a simple spending plan, but anyone who needs categories, forecasting, or multiple-account analysis will probably be happier with a separate budgeting tool alongside the card app.
What I would watch as the product evolves
The most important future improvements would be the ones that reduce uncertainty during routine card use. Clear transaction presentation, dependable account updates, understandable error messages, and a smooth recovery path after a device change would matter more to me than decorative interface changes.
I would also watch how the app handles the needs of users who are less comfortable with mobile finance. Readable text, plain explanations, and an uncomplicated route to help can make a major difference for benefit recipients. A finance app should not assume that every user understands technical terms or wants to manage several layers of settings.
Accessibility is another area worth observing. The Everyone rating communicates that the app is intended for a broad audience, but a broad audience still includes people with different eyesight, dexterity, and confidence with smartphones. In my experience, an app earns trust when important information is easy to distinguish and actions are difficult to trigger accidentally.
Finally, I would pay attention to whether future releases preserve the focused character of the service. Adding useful account controls could improve it, but adding unrelated financial features might make the experience harder for the people who use it for one essential reason. The best evolution would keep routine card management simple while making unusual situations easier to understand.
My recommendation for the right user
I would recommend Direct Express® Mobile to an eligible federal benefit recipient who wants a convenient mobile connection to a Direct Express prepaid card. The app’s strongest quality is its relevance: it is built around a specific financial need, and that can make everyday balance awareness less stressful.
I would not recommend choosing it as a general banking replacement if I needed savings management, broad account integration, or detailed financial planning. In that situation, a conventional bank app or budgeting service would be a better companion, while this app would only make sense if I also used the Direct Express card.
Overall, I see it as a practical access tool rather than a complete money-management system. Its free price removes a major barrier, and its established presence, current 9.4 version, and strong 4.6 average give me confidence that it is worth considering. Still, the real test is personal: if the Direct Express card is how benefits arrive, this app can make checking and planning easier; if not, its specialized design is precisely why it will not be useful.
My bottom line: use it for quick, responsible card awareness, keep a separate plan for broader finances, and do not let mobile convenience replace careful account security. For the people it serves, that focused approach is more valuable than a crowded list of banking features.
Pros
- Quickly check your card balance and recent transactions.
- Deposit checks remotely using your phone’s camera.
- Receive alerts for purchases, deposits, and account activity.
- Locate ATMs and participating retailers near your current location.
- Official app provides convenient access to Direct Express account tools.
Cons
- Some features may require a stable internet connection to work properly.
- Mobile check deposit availability can depend on account eligibility.
- ATM locator results may not always reflect the latest location details.
- Users may encounter login or verification steps when changing devices.
- Customer support options inside the app may be more limited than by phone.
FAQs for Direct Express® Mobile
What is Direct Express® Mobile used for?
Direct Express® Mobile is the official mobile app for eligible Direct Express cardholders. After signing in, users can review their available balance, check recent transactions, monitor deposits, locate surcharge-free ATMs, and manage certain card preferences. It is designed to provide convenient access to account information without requiring a visit to the Direct Express website or a customer service representative.
Who can use the Direct Express® Mobile app?
The app is intended for people who have an active Direct Express prepaid debit card, commonly used to receive qualifying federal benefit payments electronically. You generally need your card or account credentials and may be asked to complete identity verification before accessing features. If you do not have a Direct Express card, downloading the app alone will not create an eligible account.
Is Direct Express® Mobile safe to use for checking my benefits and card activity?
The application is built to provide secure access to Direct Express account information, using login credentials and security verification features where required. Nevertheless, users should download it only from the official Google Play Store or Apple App Store, avoid sharing passwords or one-time codes, and never sign in through links received in suspicious messages. Always keep your device and app updated.
Can I use the app to find ATMs and avoid extra fees?
Yes, Direct Express® Mobile includes tools that can help cardholders locate nearby ATMs and identify available surcharge-free options, depending on the information provided by the network and your card terms. ATM availability, withdrawal limits, and fees can vary by location and transaction type, so review the details shown in the app and confirm the terms before completing a withdrawal.
What should I do if I cannot log in or notice an unfamiliar transaction?
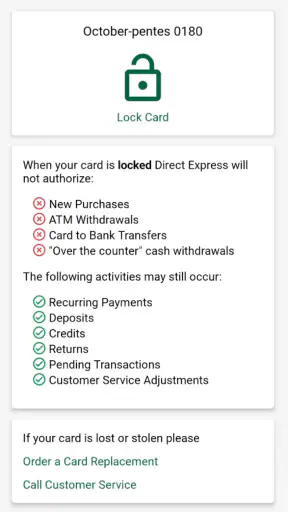
If you cannot access your account, first check that your internet connection, login details, and app version are correct. Use the official recovery or support options rather than third-party services. If you see an unauthorized transaction, a missing deposit, or a lost or stolen card, contact Direct Express customer support promptly through the official channels so your account can be investigated and protected.











